Rules
How Endorsement Income Becomes Net Worth: The Payment Chain for US Celebrities
Trace how a US celebrity endorsement dollar moves from brand to agency, manager, lawyer, tax authority, and net worth, including timing, taxes, cross-border rules.
What to take away
- Endorsement income net worth is gross deal value minus agency, manager, legal, tax, and timing costs.
- A brand deal net worth estimate often counts the headline months before the celebrity receives cash.
- How endorsement money is paid decides whether it is 1099-NEC income, wages, or loan-out corporate income.
- Cross-border deals add CRA withholding, IRS filings, and foreign tax credits.
- The public estimate often counts the headline, while the private contract controls the net.
The headline number and the net number
A brand announces a ten million dollar endorsement. Headlines call it ten million. Net worth trackers may add that figure at once. The contract may pay over three years with renewal options. The celebrity may never see the full amount. This gap is the payment chain.
Agencies, managers, lawyers, and tax authorities all take a stop. The timing of each stop changes the final net worth number. Because the deal terms stay private, endorsement income methodology explains the proxy problem in more detail.
Follow the endorsement dollar: six stops
Follow the endorsement dollar
- Brand signs the contract. The fee may be guaranteed or tied to sales. A signing bonus or endorsement fee is taxable income, as the IRS Publication 525 explains.
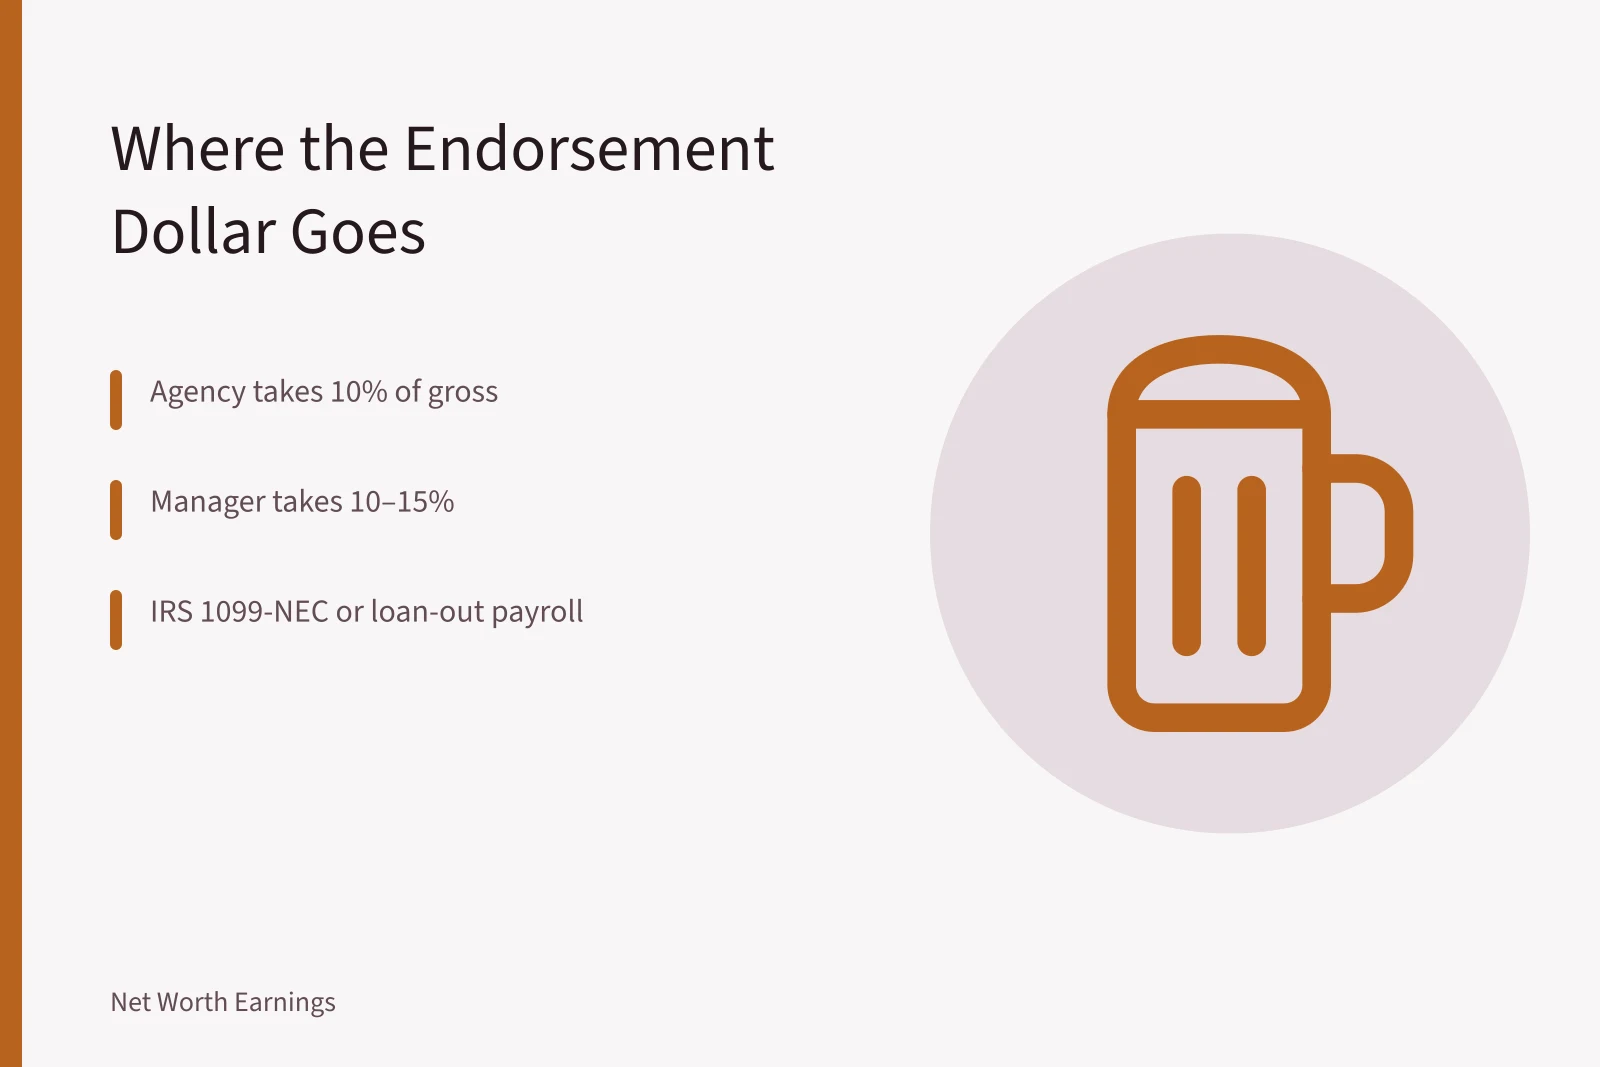
- Agency takes its commission. A talent agency often takes ten percent of gross. The check may arrive at the agency first.
- Manager takes a fee. A manager often takes ten to fifteen percent. That fee may apply to gross or net, depending on the contract.
- Lawyer and business manager bill. A lawyer may charge hourly for contract review. A business manager may charge a flat fee or percentage.
- Tax authority withholds or expects estimated payments. Federal income tax, state tax, and self-employment tax may apply. A loan-out corporation adds corporate tax and payroll tax.
- Net cash reaches the celebrity. The money may go into investments, real estate, or a business. Net worth rises only if those assets hold value. actor net worth follows the same stops, from gross screen pay to private net.
Example: a $1 million endorsement deal
This example uses common contract terms, not a real celebrity.
| Stop | What happens | Effect on net worth |
|---|---|---|
| Brand fee | Contract states gross payment | Full value often reported |
| Agency | Commission deducted from gross | Cash reduced |
| Manager | Percentage fee on gross or net | Cash reduced |
| Legal and business | Fees for review and accounting | Cash reduced |
| Tax authority | Withholding or estimated payments | Cash reduced or delayed |
| Investment | Net cash placed in assets | Value depends on return |
A net worth figure that counts the gross endorsement fee is a forecast, not a balance sheet.
The sequence changes endorsement deal earnings. If the brand pays on delivery, the celebrity may wait a year. If the brand pays on signing, the cash arrives sooner. Each delay changes the present value of the deal. The table stops short of a final figure because every contract differs. A brand may pay a flat fee. A brand may pay a base fee plus a sales bonus. The celebrity may also owe state tax in the state where the work happens.
Taxes and the timing gap
Endorsement income taxes follow the payment form. If the celebrity is a sole proprietor, the brand may send IRS Form 1099-NEC. The celebrity then pays estimated taxes each quarter. If the money goes to a loan-out corporation, the company pays tax and then payroll tax on salary.
Cross-border work adds another layer. The CRA explains tax obligations for non-residents, including withholding on Canadian-source income. A US celebrity who films a commercial in Toronto may face CRA withholding. US celebrities Canada tax covers the treaty, CRA withholding, and foreign tax credits.
Regional scenes and deal types
Where a celebrity lives and works changes the deal. Nashville country income often leans on publishing and touring. Atlanta hip-hop income often runs on features and streaming. Regional music scenes artist earnings shows why those two markets produce different cash timing.
Name, image and likeness deals show how endorsement money can be structured before a professional contract.
Why net worth estimates miss the chain
Estimators often start with fame and brand size. They then assign a deal value. But the contract may include morality clauses, exclusivity, and performance bonuses. Those terms can delay payment or cancel it. The estimator cannot see the agency commission or the tax withholdings. So the net worth figure may be too high.
A better method follows each stop. It asks who receives the money, when the money arrives, and what tax applies. That method produces a range, not a single number. The range is more useful for readers who want to understand celebrity endorsement income. A reader should treat any single endorsement figure as a starting point. The payment chain turns a contract into cash. It also turns cash into assets. Net worth is the result of that chain, not the announcement.