Reviews
Part of How to read executive pay filings and what they can and cannot show about net worth
What changes about executive net worth methodology once you look at the four breaks?
Executive net worth methodology in the one field with real filings: what documents can support, and the four places the method still breaks completely.
This is the interesting case. Everywhere else on this site the method fails because there are no documents. Here there are documents, filed under legal obligation, in a prescribed format, so executive net worth methodology gets its best possible evidence. The honest question changes: given genuine evidence, how far can an estimate actually go, and where exactly does it stop?
What to take away
- Filings support a defensible statement about one disclosed slice.
- They cannot support a balance, because they record holdings and never liabilities.
- A method that starts with real evidence and ends in invention is harder to spot.
What the documents genuinely support
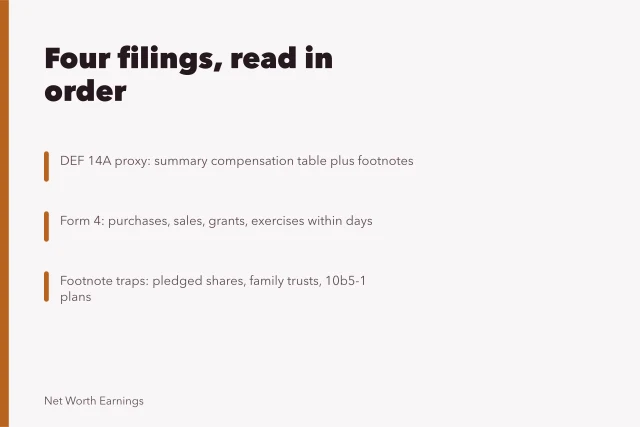
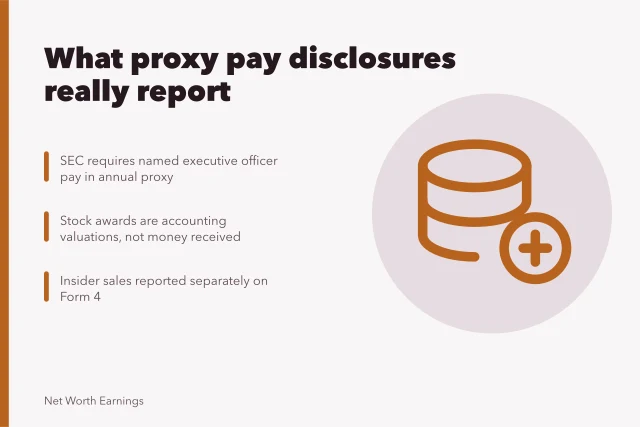
Work only from filings and a researcher can establish real things. A named officer's grants and holdings are reported on Form 3 when the person becomes an officer or director, on Form 4 whenever those holdings change, and on Form 5 once a year. Pay is disclosed in the annual proxy statement, Form DEF 14A, under Regulation S-K Item 402, the executive compensation rule that requires a Summary Compensation Table and the tables behind it. Employment agreement terms, when filed as an exhibit, appear with the annual report on Form 10-K, and beneficial ownership stakes are reported on Schedule 13D or 13G.
All of it is retrievable through the Securities and Exchange Commission's EDGAR full text search. It is dated and reproducible by anyone who repeats the search.
That is a real evidence base and it is worth more than the whole rest of this subject put together. It is also narrow in a specific way: every one of those statements is about a relationship between a person and one company.
The four breaks
The valuation break. Reported equity compensation is valued at grant, not at vesting, under the accounting standard for share-based payment, ASC 718 — the rule once known as FAS 123R. That grant-date fair value, produced by an option-pricing model in the case of options, is the company's reported cost, and it is the number that lands in the Summary Compensation Table. What the person actually receives depends on vesting and on the share price years later. Investor.gov, the commission's investor education site, sets out the distinction in its glossary entry on executive compensation, and treating the two as one number is the most common failure in the field.
Vesting is also when the tax falls due. Restricted stock and restricted stock units are taxed as ordinary income at their value on the vesting date, and the company must withhold at the statutory supplemental wage rate. A quick sale after vesting is usually that tax bill rather than a judgment about the stock, and it says nothing about net worth either way.
The four breaks in the method
What filings show
- Valuation
- Grant-date accounting value
- Coverage
- One employer's holdings
- Liability
- Shares held, unencumbered
- Timing
- True at reporting date
What is missing
- Valuation
- Value actually received later
- Coverage
- Property, trusts, other stakes
- Liability
- Pledged or borrowed-against shares
- Timing
- Stale on publication day
The coverage break. Filings describe one employer. A person may hold property, private company stakes, other listed holdings, partnership interests and family trusts, none of which appears in any of it. Disclosed holdings are a lower bound on assets and nothing more.
The liability break. This is the fatal one. Net worth is assets minus liabilities and no disclosure regime requires an individual to report personal debt. Shares can be pledged as collateral for borrowing, and a holding financed by borrowing is a very different position from an unencumbered one, yet from outside the two look identical. Proxy statements disclose the company's policy on pledging and hedging its stock, which tells you the practice exists, but not how much any individual has pledged or what else is owed.
The timing break. A holdings figure is true at a reporting date. Anything priced in a market changes daily, and the reported position is stale on the day it is published. The uncertainty that follows from that is the ordinary kind that measurement science handles openly; the NIST guidance on expressing measurement uncertainty and the Guide to the Expression of Uncertainty in Measurement (the GUM, JCGM 100) show the standard a real quantity is held to, where a value is never stated without its uncertainty.
Run the method on a live filing. Tesla's shareholder-approved 2018 CEO performance award to Elon Musk was an all-options package, with no salary attached, disclosed in the company's proxy statement on Form DEF 14A and valued at grant under ASC 718. That is the documented part: a named executive, a named company, a named document. Whether he ever realized anything from it depended on vesting and on market-capitalization milestones reached years later, and the same proxy says nothing about what he owes or what he holds outside Tesla.
Why this case is more dangerous, not less
An estimate built on nothing announces itself. An estimate built on filings for the first two steps and on invention for the rest does not. The citations are real. The documents exist. The reader sees a source and stops checking, and the invented part rides along on the credibility of the documented part.
So the audit question here is different. Not "is there a source" but "where does the sourced part end". In practice it ends after the first two lines: disclosed pay for named officers at one company, and reported holdings in that company at a date. Everything after that is modeling.
An audit you can run
Ask the article / What a good answer looks like
- Which filing, which company, which date?
- A named document with a date and a retrievable location
- Is the pay figure grant value or received value?
- An explicit statement, because they differ substantially
- Are holdings priced, and at which date's price?
- A named valuation date
- What is assumed about assets outside the company?
- Usually nothing is said, which is itself the answer
- What is assumed about liabilities?
- Almost always nothing, and pledged shares are rarely mentioned
- Is tax on vesting accounted for?
- Rarely, and it is a large omission
Any article that answers fewer than four of these is presenting a modeled number as a documented one.
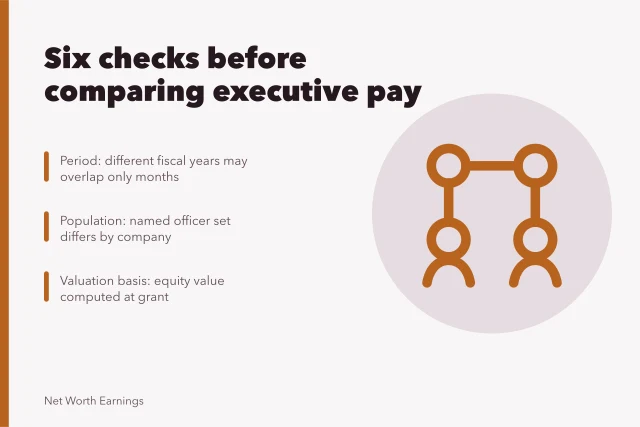
Six questions to audit the number
- Which filing, company and date?
- Grant value or received value?
- Priced at which valuation date?
- What is assumed about outside assets?
- What is assumed about liabilities?
- Is tax on vesting accounted for?
The honest output
A statement about a documented slice, dated and narrow. A range for anything wider, with the range wide enough to admit that liabilities are unknown. Or a refusal, with the reasoning shown. Those are the same three outputs as everywhere else, which is the point: better evidence improves the first option and does not rescue the third.
The general form of the argument is on estimate methodology, and the components of disclosed pay are on executive net worth. The reason ranked tables cannot survive this standard is on richest rankings, and the way employment terms are negotiated and reported is on contracts and salaries.
Common questions
If filings are public, why does no one publish an audited executive figure?
Because the audit would fail at the liability step. Anyone can publish what a filing says about disclosed pay and holdings. Nobody can publish what a person owes, so a net figure cannot be closed.
Do foreign-listed executives have the same disclosure?
Different rules, different formats, different thresholds, and in some markets a great deal less. A method built on one country's regime does not transfer, and cross-market comparisons frequently assume it does.
Does a large share sale reveal wealth?
It reveals a transaction. It says nothing about why, since sales are often scheduled in advance or made to cover a tax bill on vesting, and nothing about what the person holds elsewhere.